

The Curlew
Semi-Detached House
Part of the Top Farm, Nuneaton development
Share this development
The property
Introducing The Curlew, 2 bedroom semi-detached home at Top Farm.
This beautifully designed two-story home offers 782 square feet (NIA) of modern living space, perfect for families or professionals seeking comfort and functionality.
Ground Floor: Upon entry, you’re greeted into the kitchen/dining area attached to a stylish WC and a separate staircase. The rear of the home features a living area with french doors that open to the garden, enhancing outdoor living.
First Floor: Upstairs, you'll find two generously sized bedrooms. These share a well-appointed family bathroom. A central landing connects all rooms.
This thoughtfully laid-out home offers both style and practicality, making it an excellent choice for comfortable, contemporary living.
This development is subject to a local connection to Nuneaton and Bedworth.
The Curlew is just one of the many property types available at Top Farm in Nuneaton, Warwickshire, a stunning development that has been developed from the ground-up to offer sustainable, modern living.
With two, three and four-bedroom houses for sale, Top Farm is the ideal choice for any families, young couples, first-time buyers or downsizers that are looking to purchase near popular destinations such as Warwick, Nuneaton and Leamington.
As with all of the property types across Top Farm, The Curlew benefits from air source heating, solar panels and EV charging points, making it a clear prospect for anyone looking to save money on utilities whilst living in a contemporary, thoughtfully-designed property.
Residents of Top Farm also benefit from having Nuneaton just minutes away, a popular market town that offers a vast array of things to see and do such as pubs and restaurants, high-street retailers, independent boutiques and other key amenities.
Features and description
-
 10 year build warranty
-
 Air source heating
-
 Electric Charging Point
-
 Solar Panels
-
 Downstairs WC
-
 Stainless steel oven, hob & extractor
-
 Allocated parking
-
 Double glazed windows
-
 En suite
-
 Plumbing for washing machine

Top Farm Development Brochure
To learn more about the Top Farm development and house types on site, download the development brochure.
Download Development Brochure
Top Farm, Nuneaton Site plan
Status
Local Area Information
Am I eligible?
Shared Ownership uses the following criteria to help people get a foot on the housing ladder:- Maximum annual household income of £80,000
One of the following statements must also be true:
- You’re a first-time buyer
- You used to own a home but can’t afford to buy now
- You’re forming a new household - typically after a relationship breakdown
- You’re already part of the Shared Ownership scheme but want to move
- You own a home and want to move but can’t afford the new home that meets your needs
Use the Shared Ownership mortgage calculator to estimate the cost of buying this home
You can purchase between 10% and 75% of the property's full market value. Each home benefits from a 10 year repair period for essential repairs.
You are able to buy more of your home through the Staircasing process, where you can purchase shares in increments of 5%. There is also the option of the 1% Gradual Staircasing Model enabling you to purchase smaller shares each year.
Enquire about this property

Frequently asked questions
Most buyers who can’t afford to buy a home outright can apply to buy through shared ownership.
We may also be able to help if you need to move because of a relationship breakdown or if your work requires you to live in an area outside your price range.
In order to buy through the Shared Ownership scheme, you must be able to demonstrate that you can afford and sustain home ownership. If you proceed with Shared Ownership you will be required to undertake an affordability assessment.
You must meet our adverse credit policy, if you have a history of adverse credit you are unlikely to be accepted depending on individual circumstances.
Shared owners still have to pay many of the usual costs involved in buying a home.
Reservation fee
We will ask you for a £250 deposit to reserve your chosen home. When the sale goes through we put this towards your purchase payments. However, we cannot refund it if the sale does not go through.
Mortgage deposit and fees
Most mortgage lenders will ask for a 5% or 10% deposit towards the price of the share you want to buy. They are also likely to charge a valuation fee and administration fees.
Legal fees
Solicitors’ charges can vary so it is best to get a few estimates. You will also have to pay Land Registry and local search fees, and may have to pay stamp duty depending on the value of the property.
After you've moved in
You also need to budget for the ongoing costs of owning a home.
Mortgage repayments
You will have to make monthly mortgage repayments to your lender. Depending upon the type of mortgage you have, these repayments may vary as interest rates change.
Rent
You pay a subsidised monthly rent to us on the share of your home which we own. The amount is reviewed on the 1st April each year.
Service charges
You will have to pay a small charge if your home has any facilities or communal areas which we maintain, such as shared entrance halls, lighting and grounds. Your service charge will also include your buildings insurance and your management fee.
Household bills
These include your council tax and utility bills for water, gas and electricity.
Repairs
We will arrange for any defects on new-build homes to be repaired during a set time period. After that time has elapsed, you will be responsible for arranging and paying for all repairs to your home.
Home contents insurance
We provide buildings insurance with the cost of your service charge but this does not cover your belongings. We strongly recommend you arrange your own home contents insurance.
Much will depend on your other financial commitments and what property/share you want to buy. We don't want you to be overstretched, so we need to be sure that you can afford to pay your mortgage and rent. We look at each application individually and will advise you on your options.
Shared ownership schemes are backed by government funding to help people on smaller incomes. So you will not qualify for most shared ownership schemes if your household income is less than £10,000 or more than £80,000 a year.
On the property listings for some of our shared ownership homes, you will see that we state a local connection to the area is required.
This generally applies in rural areas and small villages where land has been made available specifically for affordable housing to meet the needs of local people, rather than for private development.
These are known as ‘rural exception sites’ or 'protected areas' and are controlled by ‘Section 106 Agreements’. They aim to help local people and families afford homes in the area where they grew up.
The local connection criteria can vary between different developments, but is usually based on the following:
applicant was born in the area and has lived there for a number of years
applicant has permanently lived in the area for a number of years
applicant used to live in the area for a number of years but had to move away because of the lack of affordable housing
applicant has been permanently employed in the area for a number of years
The number of years is usually between 2 and 5, although this differs by local authority
Usually priority is given to applicants with a local connection to the parish. If there are still properties remaining, allocation will be opened up to surrounding parishes and then to the whole of the local authority area. This ensures that the homes are occupied by residents as local to the area as possible.
If you want to find out more about the local connection criteria for a particular development, or check if you qualify, please email sales@platformhg.com
Yes you can, once you have moved into your Shared Ownership property, providing you can afford it, you are able to buy more of your home through the process of Staircasing.
- Available
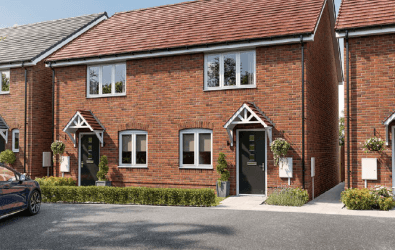
The Atkins
Semi-Detached House
Part of Top Farm, Warwickshire, Nuneaton Price from £25,000 for a 10% share Register your interest - Available
The Weaver
Mid-Terraced House
Part of Loomcroft, Keresley, Keresley Prices from £104,000 for a 40% share Register your interest - Available
The Atkins, Semi-Detached
Semi-Detached House
Part of The Spires, Coventry, Coventry Prices from £27,000 for a 10% share Register your interest - Sold Out
The Ivy
Semi-Detached House
Part of Kingmakers View, Warwickshire, Wolvey Sold Out Register your interest - Sold Out

The Chestnut
Semi-Detached House
Part of Kingmakers View, Warwickshire, Wolvey Sold Out Register your interest - Apply Now
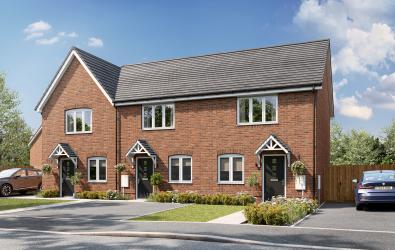
The Atkins, Terraced
Terraced House
Part of The Spires, Coventry, Coventry Prices from £26,000 for a 10% share Register your interest -
- Sold Out
The Maybach
Semi-Detached House
Part of Whitley Mews, Baginton, Baginton Sold Out Register your interest - Coming Soon

Two bedroom homes
Semi-Detached House
Part of Colebrook, Solihull Price to be confirmed Register your interest -